Fair value measurement is one of the most judgment-intensive areas of fund financial reporting. For fund managers holding less liquid positions, from private equity and venture capital stakes to OTC derivatives and digital assets, valuation decisions flow directly into NAV, investor reporting, and the annual fund audit. As our guide puts it, the application of fair value remains an art, not a science.
Valuation also remains a regulatory focus. The SEC Division of Examinations lists valuation among the core areas it reviews when assessing the effectiveness of investment advisers’ compliance programs, and it specifically flags valuation for advisers that have not previously advised private funds, according to its Fiscal Year 2026 Examination Priorities.
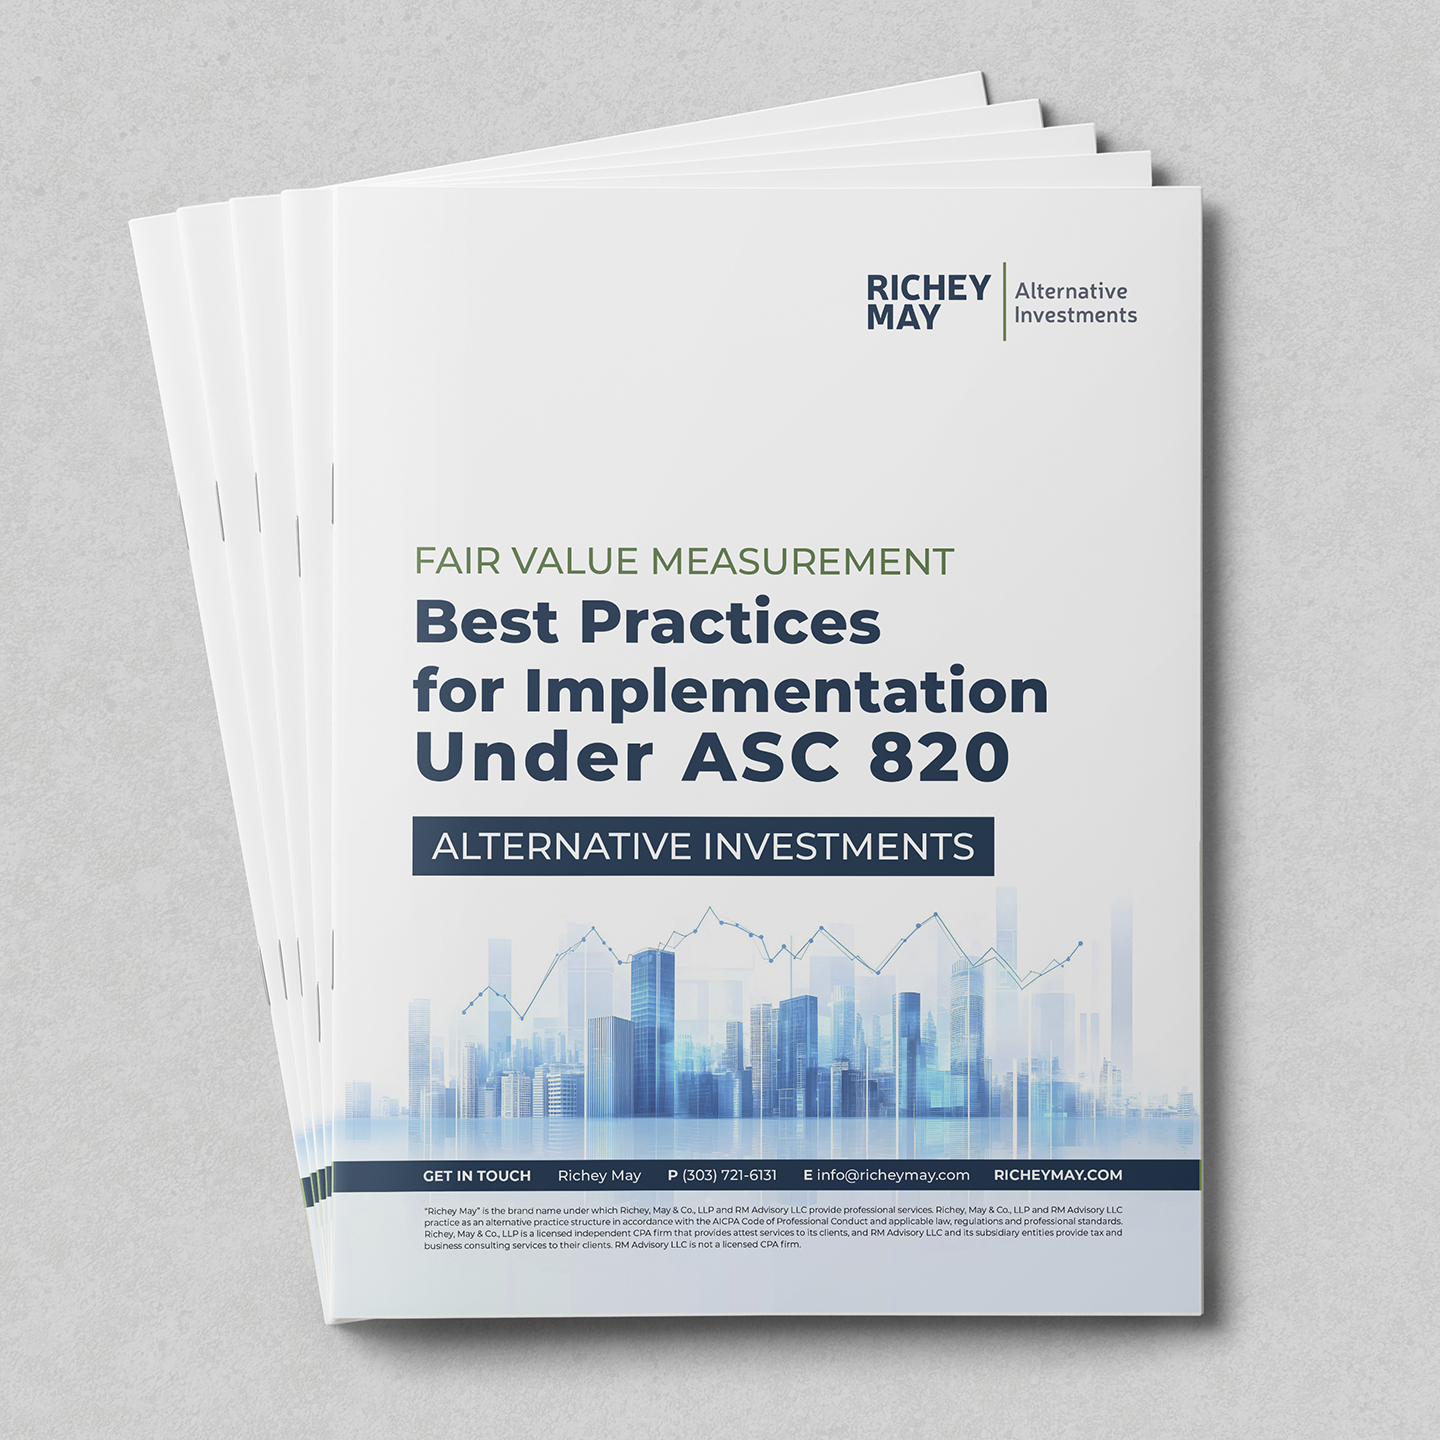
Richey May’s guide, Fair Value Measurement: Best Practices for Implementation Under ASC 820, gives fund managers and the finance teams at their management companies a practical framework for applying the standard across alternative investments. We ensure this guide is up to date every year and have updated it for 2026 to reflect refinements in practice and new guidance on digital asset pricing.
What’s New in the 2026 Edition
This edition sharpens several areas where fair value practice has evolved:
- Valuation techniques for illiquid investments. The guide frames the use of multiple valuation techniques as general good practice for corroborating fair value, while recognizing that a single well-supported method may be appropriate depending on the facts.
- Level designations. Updated language emphasizes disciplined judgment and avoiding overstated observability when assigning levels to securities with unobservable inputs.
- NAV practical expedient. The guide clarifies that fund investments measured using NAV as a practical expedient are not categorized within Level 1, 2, or 3, but still require separate disclosure.
- Digital asset pricing. New content addresses aggregated pricing sources, such as volume-weighted prices across multiple exchanges, and whether a specific exchange represents the principal market. Guidance on illiquid digital assets acquired through an initial coin offering has also been refined.
View the ASC 820 Guide
“Our team has assembled this guide after much discussion with our clients and other industry leaders regarding key topics that relate to Fair Value and ASC 820,” said Steve Vlasak, Business Development Partner of the Alternative Investments practice. “This is certainly a critical area of focus for our clients and friends in the alternative investments industry as well as an area that the SEC focuses on very closely. We are excited to be releasing this whitepaper, and believe it will be a great resource to help improve the understanding of these standards.“
What the Guide Covers
Core Fair Value Concepts
The guide walks through key definitions, including exit price, principal market, valuation techniques, observable and unobservable inputs, and the fair value hierarchy. It also addresses inactive markets, liabilities, portfolio-level measurement, counterparty risk, premiums and discounts, and transaction costs.
Level Designations and Disclosures
Readers will find considerations for each level of the hierarchy, including investments in private operating companies and private investment companies, along with disclosure requirements for Level 3 activity, inputs and valuation techniques, and differences between U.S. GAAP and IFRS.
Sample Financial Statement Disclosures and FAQs
Exhibits include sample fair value notes for both a hedge fund and a private equity fund, sample disclosures for investments in private investment companies, a sample digital assets valuation memo, and frequently asked questions on third-party pricing, broker-dealer quotations, and each level of the hierarchy.
What’s Next
If you have questions about the guide or about the services Richey May provides to hedge funds, private equity funds, and other alternative investments clients, contact Steve Vlasak at svlasak@richeymay.com.